TimesFM: Google's Time Series Foundation Model, and the Licence Split at Version 3.0
TimesFM (Time Series Foundation Model) is a pretrained time-series foundation model developed by Google Research for time-series forecasting.
At a glance
- What is it?
- TimesFM is a pretrained decoder-only forecasting model from Google Research. The code is Apache-2.0, but the TimesFM 3.0 weights are not, and that distinction decides whether you can ship it.
- Who is it for?
- Adopt TimesFM if you need zero-shot forecasts over many short or irregular series and can work inside the 3.0 weight licence, or if you can stay on 2.5 weights under Apache-2.0. Do not adopt it for a production commercial system on the default 3.0 checkpoint, because the repository states that commercial or production use of those weights is not permitted.
- Can I use it commercially?
- Yes. Apache-2.0 is a permissive licence: you can use, modify and sell software built on it, as long as you keep its copyright and licence notices.
- Is it still maintained?
- Yes. The repository received new commits within the last day.
- What is it written in?
- Mainly Python, according to GitHub's language statistics.
Answers come from the project's GitHub data, last synced on November 13, 2026, and from our analysis. They are not legal advice.
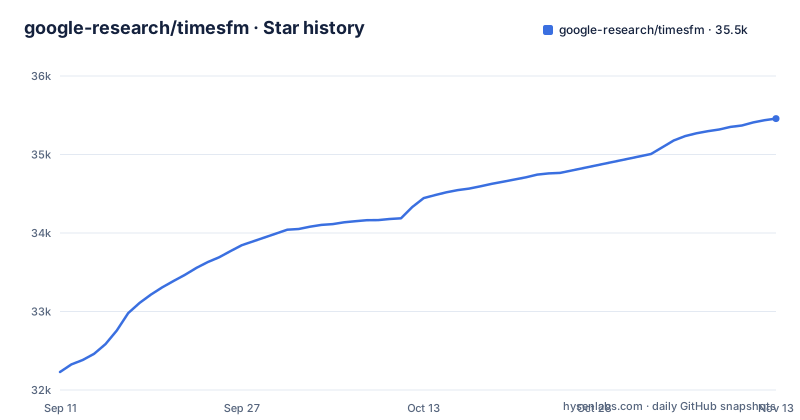
Star history
- google-research/timesfm35,457 ★ · +3,228
| Repository | 2026-09-11 | 2026-11-13 |
|---|---|---|
| google-research/timesfm | 32.2k | 35.5k |
3,228 Stars in the last 63 days, measured from the daily GitHub snapshot. Compare with other projects
Editorial analysis
The forecasting problem TimesFM is aimed at
Most forecasting code in production is per-series: you pick a model class, fit it to one product's demand history or one sensor's readings, tune it, and repeat. That works when you have a handful of well-understood series and enough history to fit each one. It breaks down when the series count runs into the thousands, when many of them are short, or when new series appear with no history at all. TimesFM is built for that second situation. It is a pretrained foundation model, so the README's framing is zero-shot generalist forecasting: you pass in context windows and get forecasts back without training on your data. The README also notes that the open version is not an officially supported Google product, which matters if you were expecting an SLA. The supported commercial routes named in the README are separate: BigQuery ML, Google Sheets, and Vertex Model Garden.
What changed in TimesFM 3.0, and what 2.5 already did
Version 3.0, released August 2026, adds native multivariate forecasting and covariate support, covering both past-only and past-and-future dynamic covariates, described in the README as working without per-task tuning. That is the substantive change: earlier versions were univariate. The 2.5 release, from September 2025, is where several practical properties were set. It uses 200M parameters against 2.0's 500M, supports up to 16k context length against 2048, adds a continuous quantile forecast up to a 1k horizon through an optional 30M quantile head, and removes the frequency indicator that earlier versions required. So the migration story is not only about accuracy. Dropping the frequency flag removes a piece of per-series metadata you previously had to supply correctly. A 16k context is roughly eight times the 2.0 window, which changes what counts as a usable history. The README's benchmark claims for 3.0 (rank #1 on fev-bench, TIME, and GIFT-Eval) are the project's own reported results; treat them as a starting hypothesis for your data, not a substitute for a backtest.
The mechanism: a decoder-only model over patched context
The paper title in the README is explicit: a decoder-only foundation model for time-series forecasting. The architecture follows the language-model pattern rather than the encoder-decoder pattern used by many sequence models. In practice that means the model consumes a context window and emits the continuation, and the Python surface reflects it. In the 3.0 example, you construct a ModelConfig with a checkpoint path, a per_core_batch_size, and a device, wrap it in a TimesFM3Evaluator. The README describes passing a batch of 1D NumPy arrays of different context lengths. The example uses two series of different lengths, 100 and 72 steps, to show that variable-length input is accepted. For Apple silicon, the README offers MLX-native inference via pip install timesfm[mlx], with no PyTorch required.
Installing TimesFM and loading a checkpoint
The README gives two PyPI paths, distinguished by backend. For PyTorch, pip install timesfm[torch]. For MLX-native inference on Apple silicon, with no PyTorch required, pip install timesfm[mlx]. For a local checkout, the documented sequence is git clone, cd into the directory, then create a virtual environment and install in editable mode with the torch extra. The README shows uv for this: uv venv, source .venv/bin/activate, then uv pip install -e .[torch]. The 3.0 code path imports from timesfm3, not timesfm, and the checkpoint is named as google/timesfm-3.0-pytorch in the ModelConfig. Older checkpoints live elsewhere in the tree: 2.5 code is under src/timesfm, and 1.0 and 2.0 code is archived in a subdirectory called v1. To load those older models the README points at pip install timesfm==1.3.0. The version pin matters because the archived code under v1 belongs to the older releases. The README also records that PyPI was updated to timesfm=2.0.2 in July 2026, so the package version and the model version you intend to run are two separate decisions.
The licence split between code and weights
This is the part to read before anything else. The README states that the source code in the repository is Apache-2.0 and that model weights up to version 2.5 remain Apache-2.0. TimesFM 3.0 pretrained weights are distributed under a separate timesfm-non-commercial-license-v1.0, restricted to non-commercial, non-production use. The README's own wording is that commercial or production use of downloaded / self-hosted weights is not permitted. The practical consequence is that the permissive licence on the code tells you very little about what you may deploy. Fine-tuning does not obviously resolve this: the README documents a LoRA fine-tuning example using HuggingFace Transformers and PEFT, but it does not state that a fine-tuned derivative of the 3.0 weights escapes the weight licence. If your use is commercial, the safe reading is to stay on 2.5 weights or take one of the hosted routes the README names. This is a description of what the repository says, not legal advice; get your own review before shipping.
Where TimesFM is the wrong tool
The clearest failure mode is not a bug, it is a licence boundary. A commercial forecasting product loading the default 3.0 checkpoint is outside the stated terms. The second is scope. TimesFM is a generalist model; if you have one series with a decade of clean history and a known seasonal structure, a fitted statistical or gradient-boosted model with your own features will usually be easier to explain to whoever signs off on the numbers, and it carries no weight licence at all. The third is cost shape. A foundation model pays off through amortisation across many series, and the README's own batching parameter, per_core_batch_size, is a reminder that throughput depends on how you feed it. If your workload is a few dozen series refreshed hourly, the inference overhead may not be repaid. Fourth, the README text in this repository gives no figures for memory requirements or expected latency, so measure them on your own hardware before committing.
How TimesFM differs from the obvious alternatives
The nearest comparison is not another library but a different method. A per-series pipeline built on something like statsmodels or a gradient-boosted forecaster fits parameters to your data and lets you inspect them. TimesFM fits nothing at inference time; it applies pretrained weights to a context window. That is the whole trade: you give up per-series interpretability and the ability to inject domain structure directly, and you get a forecast for a brand-new series with no fitting step. The second comparison is a general sequence model such as a transformer trained on your own history. That route can beat a generalist on a narrow domain, but it requires labelled training data, a training loop, and retraining as the domain drifts, none of which TimesFM asks for. The third is the hosted route inside Google's own stack. BigQuery ML and Vertex Model Garden expose TimesFM without you managing checkpoints or weights, which sidesteps the licence question by moving it into the service terms. If your data already lives in BigQuery, that path is worth pricing against self-hosting before you build anything.
Maintenance, versioning, and upgrade cost
The upgrade surface is wider than a typical library. Three things version independently: the PyPI package, the model checkpoint, and the import path. The 3.0 example imports from timesfm3, while 2.5 code sits under src/timesfm and 1.0 and 2.0 code is archived under v1 behind a pinned pip install timesfm==1.3.0. Moving from 2.5 to 3.0 therefore is not just a version bump; it can mean a different module, a different checkpoint identifier, and a different licence. The 2.5 line also changed behaviour in ways that affect existing code: the frequency indicator was removed, so any pipeline that sets it needs revisiting, and the context length moved from 2048 to 16k. The repository has an active release cadence, with 2.0.1, 2.0.2, and 3.0.0 all appearing within roughly three months, so pinning both the package version and the checkpoint path is the minimum discipline. The README credits community contributions for the AGENTS file, the SKILL.md under timesfm-forecasting, the fine-tuning example, and unit tests under tests, which suggests the peripheral tooling moves faster than the core model documentation.
Editorial conclusion
Adopt TimesFM if you need zero-shot forecasts over many short or irregular series and can work inside the 3.0 weight licence, or if you can stay on 2.5 weights under Apache-2.0. Do not adopt it for a production commercial system on the default 3.0 checkpoint, because the repository states that commercial or production use of those weights is not permitted. Before committing, verify three things: which licence covers the exact checkpoint you intend to load, whether your series are long enough to benefit from a 16k context rather than a per-series model, and whether the MLX or PyTorch backend matches your hardware, since the README presents them as separate install extras.
Frequently asked questions
What is Google's TimesFM?
TimesFM, which stands for Time Series Foundation Model, is a pretrained time-series foundation model developed by Google Research for time-series forecasting. The underlying paper is A decoder-only foundation model for time-series forecasting, arXiv 2310.10688, published at ICML 2024, and the current version is TimesFM 3.0 with native multivariate forecasting and covariate support.
How good is TimesFM?
The project's own notes for 3.0 claim rank number one overall on fev-bench across 100 real-world forecasting tasks, rank number one overall on the TIME benchmark across 50 domain datasets and 98 evaluation tasks, and rank number one among all foundation models on GIFT-Eval. These are the project's own reported figures rather than an independent comparison.
How do I install TimesFM?
From PyPI, `pip install timesfm[torch]` for the PyTorch path, or `pip install timesfm[mlx]` for MLX-native inference on Apple silicon with no PyTorch required. A local install clones the repository and uses uv to create a virtual environment and install in editable mode with the torch extra. The base package alone contains only numpy, huggingface_hub and safetensors, so a framework extra is required.
Is TimesFM open source?
The source code in the repository is licensed under Apache-2.0, and model weights up to version 2.5 remain Apache-2.0. TimesFM 3.0 pretrained weights are the exception: they are under a separate non-commercial licence and are restricted to non-commercial, non-production use, so the open code and the current weights are not under the same terms.
Is TimesFM multivariate?
Yes, natively, as of TimesFM 3.0. The release adds native multivariate and univariate forecasting with support for past-only and past-and-future dynamic covariates without per-task tuning, which is a change from earlier versions, where covariate support for 2.5 arrived through XReg in October 2025.
How do I use TimesFM?
The 3.0 example passes a batch of 1D NumPy arrays of different context lengths to a TimesFM3Evaluator built from a ModelConfig holding a Hugging Face checkpoint path, a per-core batch size and a device. Earlier versions are still reachable: the code for 1.0 and 2.0 is archived in the v1 subdirectory, and the older package can be installed with `pip install timesfm==1.3.0`.
Official sources
Add this badge to your README
If you maintain this project, the badge below links readers to this analysis and shows its maintenance status from the daily GitHub snapshot. Paste the markdown into your README; add ?metric=license or ?metric=stars to the image URL for a different field.
[](https://hysenlabs.com/projects/google-research-timesfm)Star history chart for your README
[](https://hysenlabs.com/projects/google-research-timesfm)Was this useful?