je-suis-tm/quant-trading: Python Backtests for Seventeen Strategies, Without the Execution Layer
Python quantitative trading strategies including VIX Calculator, Pattern Recognition, Commodity Trading Advisor, Monte Carlo, Options Straddle, Shooting Star, London Breakout, Heikin-Ashi, Pair Trading, RSI, Bollinger Bands, Parabolic SAR, Dual Thrust, Awesome, MACD
At a glance
- What is it?
- A collection of Python scripts that backtest technical indicator, options and quantamental strategies on historical data, with a global main function for embedding. It is a research and teaching codebase, not a trading system, and the README states the frictionless assumption plainly.
- Who is it for?
- Adopt it if you want readable Python implementations of MACD, pair trading, Dual Thrust, Bollinger Band pattern recognition, VIX calculation or options straddle logic to study, modify or embed through the main function. Do not adopt it as a live trading system: the README states trades are assumed frictionless, there is no HFT code, and there is no documented execution, risk or order management layer.
- Can I use it commercially?
- Yes. Apache-2.0 is a permissive licence: you can use, modify and sell software built on it, as long as you keep its copyright and licence notices.
- Is it still maintained?
- Yes. The repository last received commits 148 days ago.
- What is it written in?
- Mainly Python, according to GitHub's language statistics.
Answers come from the project's GitHub data, last synced on November 13, 2026, and from our analysis. They are not legal advice.
Star history
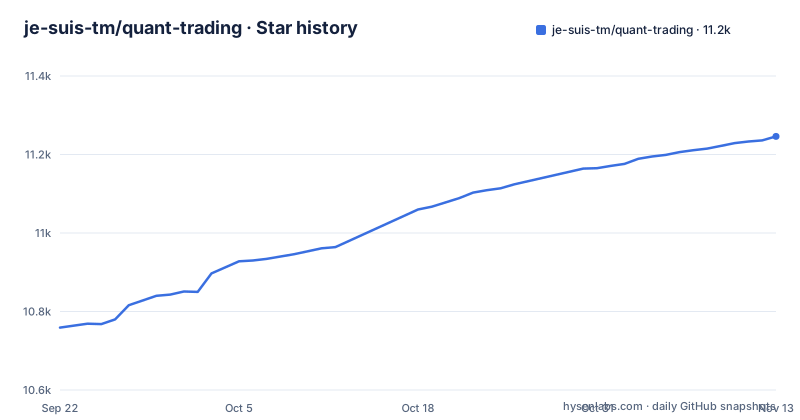
- je-suis-tm/quant-trading11,246 ★ · +487
| Repository | 2026-09-22 | 2026-11-13 |
|---|---|---|
| je-suis-tm/quant-trading | 10.8k | 11.2k |
487 Stars in the last 52 days, measured from the daily GitHub snapshot. Compare with other projects
Editorial analysis
What je-suis-tm/quant-trading actually is, and who it is written for
The repository is a personal collection of Python backtesting scripts rather than a framework. The README describes the contents as mostly technical indicator automated trading, covering momentum trading, opening range breakout, reversal of support and resistance, and statistical arbitrage, with a smaller set of quantamental projects. The audience is implied by that framing: someone who already understands what a moving average crossover means and wants working code to inspect. The README opens with quotes from Robert Mercer and Elwyn Berlekamp, sourced from Gregory Zuckerman's book, which sets the tone as much as the syllabus. You read the script, you run it, you change it. The README is explicit that all scripts contain a global function named main so the code can be embedded into a trading system, and equally explicit that docstrings are missing. That combination defines the project: the interface is the source file.
How the strategies are structured: one file per idea, shared data assumptions
The top-level layout is flat and self-describing. Each strategy is a single script, for example MACD Oscillator backtest.py, Pair trading backtest.py, Dual Thrust backtest.py, Heikin-Ashi backtest.py, London Breakout backtest.py, Parabolic SAR backtest.py, RSI Pattern Recognition backtest.py, Bollinger Bands Pattern Recognition backtest.py, Awesome Oscillator backtest.py, Shooting Star backtest.py, Options Straddle backtest.py and VIX Calculator.py. Larger ideas live in directories such as Monte Carlo project, Oil Money project, Smart Farmers project, alongside data and preview folders holding inputs and chart images. The README describes MACD as computing long and short moving averages on close price and going long when the short average sits above the long one. Pair trading is described as an Engle-Granger two step analysis on two cointegrated stocks, standardizing the residual and setting one sigma away on both tails as the threshold, then going long the cheap leg and short the expensive one. Those two descriptions are enough to see the pattern: the math lives in the script, and there is no shared abstraction layer between strategies.
Installing and running a first backtest
The repository has no GitHub releases and its top level is a set of Python scripts, so the route is cloning the repository and running a script directly with a Python interpreter. The data sources listed in the README include the yfinance and fix_yahoo_finance packages.
git clone https://github.com/je-suis-tm/quant-trading.git
cd quant-trading
python "MACD Oscillator backtest.py"
The repository ships preview images under preview/. The README lists Bloomberg, Eikon, CME, LME, Histdata, FX Historical Data, Macrotrends, Stooq, Quandl, Reddit WallStreetBets and Yahoo Finance as inputs across the project, and no single feed covers every script. Check the import block at the top of the file you are running before changing anything else. Because every script exposes main, the intended embedding path is to import the file and call that function from your own harness rather than to shell out to it.
The frictionless assumption is the limitation that matters
The README states that all scripts are historical data backtesting and forward testing in Python, and that the assumption is that all trades are frictionless, with no slippage, no surcharge and no illiquidity. That single sentence bounds what the reported results mean. A London Breakout or Dual Thrust backtest that fills at the signal price will look better than any live implementation of the same rule, and the gap is not a bug you can patch inside the strategy file. There is also no execution layer at all: no order routing, no position sizing framework, no risk controls, no broker adapter. The README is candid that there is no HFT strategy, because ultra high frequency data are expensive to acquire even via platforms like Quantopian or Quandl. Anyone arriving from a search for a trading bot should read that as a boundary rather than a gap to be filled later. The scripts are also not packaged as a library, so version pinning, dependency resolution and upgrade paths are your problem, not the project's.
Where it sits next to vectorized backtesting libraries
The natural alternative is a backtesting framework such as Backtrader, which inverts the design. It gives you a common event loop, a broker model with commission and slippage parameters, and a portfolio object, and you supply the signal logic as a small class or function. je-suis-tm/quant-trading does the opposite: the signal logic is the script, and there is no shared engine. The trade-off is concrete. With a framework you get consistent fills and comparable metrics across strategies but you spend time learning the framework's abstractions. With these scripts you get direct access to the indicator math and no abstraction tax, but every result carries the frictionless caveat and you cannot compare two strategies on equal footing without building the harness yourself. For learning how an indicator produces a signal, the flat script wins. For deciding whether a strategy survives costs, the framework wins, because it can model the costs this repository assumes away.
Maintenance, licence and the cost of staying current
The repository is not archived, and the last push was on 2026-06-20. That is recent enough that the code has not been abandoned, but the repository has no published releases. Upgrading therefore means pulling master and re-reading the diff of whichever script you depend on, since a change to a shared indicator formula will not announce itself. The Apache-2.0 licence permits commercial use, modification and redistribution provided you keep the licence and notices and state significant changes, and it includes a patent grant. It does not cover the data. Bloomberg and Eikon feeds are licensed separately, Yahoo Finance and yfinance access is governed by their own terms, and redistributing scraped CME or LME data may not be permitted at all. That distinction matters more than the code licence for anyone planning to publish results or ship a product. None of this is legal advice; read the licence text and the terms of each feed you use.
Editorial conclusion
Adopt it if you want readable Python implementations of MACD, pair trading, Dual Thrust, Bollinger Band pattern recognition, VIX calculation or options straddle logic to study, modify or embed through the main function. Do not adopt it as a live trading system: the README states trades are assumed frictionless, there is no HFT code, and there is no documented execution, risk or order management layer. Before relying on any script, verify the data source it expects, since the README lists Bloomberg/Eikon, CME, LME, Histdata, Stooq, Quandl, Yahoo Finance and others rather than a single bundled feed.
Frequently asked questions
What is je-suis-tm/quant-trading?
It is a Python repository of backtesting scripts for quantitative trading strategies, including MACD, pair trading, Dual Thrust, Heikin-Ashi, London Breakout, Parabolic SAR, RSI and Bollinger Band pattern recognition, options straddle, a VIX calculator and several quantamental projects. All scripts expose a global main function so you can embed them in your own system.
Does je-suis-tm/quant-trading support live trading or order execution?
No. The README describes the scripts as historical data backtesting and forward testing only, and states there is no HFT strategy because ultra high frequency data are expensive to acquire.
What data sources does je-suis-tm/quant-trading expect?
The README lists Bloomberg, Eikon, CME, LME, Histdata, FX Historical Data, Macrotrends, Stooq, Quandl, Reddit WallStreetBets and Yahoo Finance with the yfinance and fix_yahoo_finance packages. No single feed covers every script, so check the imports in the file you run.
Are the backtest results in je-suis-tm/quant-trading realistic?
The README states the assumption is that all trades are frictionless, with no slippage, no surcharge and no illiquidity, so reported results do not include trading costs. Treat them as illustrations of strategy mechanics rather than estimates of live performance.
What licence applies to je-suis-tm/quant-trading?
The repository is licensed under Apache-2.0, which permits commercial use and modification subject to keeping the licence and notices and stating significant changes. The market data the scripts consume is licensed separately and is not covered by that licence.
Official sources
Add this badge to your README
If you maintain this project, the badge below links readers to this analysis and shows its maintenance status from the daily GitHub snapshot. Paste the markdown into your README; add ?metric=license or ?metric=stars to the image URL for a different field.
[](https://hysenlabs.com/projects/je-suis-tm-quant-trading)Star history chart for your README
[](https://hysenlabs.com/projects/je-suis-tm-quant-trading)Was this useful?