Finance Toolkit: 500 financial metrics with the arithmetic left visible
Transparent and Efficient Financial Analysis
At a glance
- What is it?
- A Python library that computes ratios, models, risk, performance and now econometrics from raw statements, so you can read the formula instead of trusting a vendor's black box.
- Who is it for?
- Finance Toolkit earns its place when a metric's definition matters more than its availability, which is exactly the case the README argues with eight different price-to-earnings figures for Microsoft on the same day. The formulas live in files you can read, and the README's functionality sections walk through real analyses.
- Can I use it commercially?
- Yes. MIT is a permissive licence: you can use, modify and sell software built on it, as long as you keep its copyright and licence notices.
- Is it still maintained?
- Yes. The repository last received commits 1 day ago.
- What is it written in?
- Mainly Python, according to GitHub's language statistics.
Answers come from the project's GitHub data, last synced on November 21, 2026, and from our analysis. They are not legal advice.
Star history
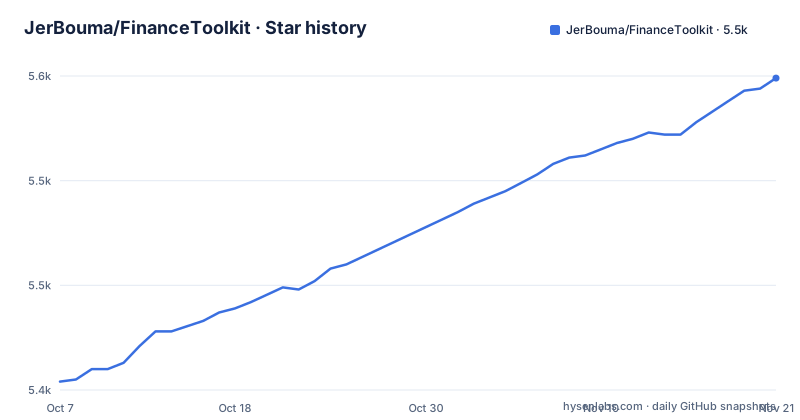
- JerBouma/FinanceToolkit5,549 ★ · +145
| Repository | 2026-10-07 | 2026-11-21 |
|---|---|---|
| JerBouma/FinanceToolkit | 5.4k | 5.5k |
145 Stars in the last 45 days, measured from the daily GitHub snapshot. Compare with other projects
Editorial analysis
Eight price-to-earnings figures for one company on one day
The README opens with a problem rather than a feature list. On the sixth of May 2023, the Price-to-Earnings ratio for Microsoft is reported as 28.93 by Stockopedia, 32.05 by Morningstar, 32.66 by Macrotrends, 33.09 by Finance Charts, 33.66 by Y Charts, 33.67 by the Wall Street Journal, 33.80 by Yahoo Finance and 34.4 by Companies Market Cap. All eight are correct, because each applies a different definition, and the definitions are frequently hidden behind a paid subscription.
That is the design constraint. The project presents itself as a toolkit of more than 500 financial methods written down in the simplest way possible, with the intent that the calculation method is transparent rather than asserted. The README links to `financetoolkit/ratios/valuation_model.py` as proof of that claim.
The practical consequence is a different relationship with your numbers. Instead of accepting a provider's ratio, you can compute it from statements you have inspected and see exactly which denominator was used. That matters most for the metrics where providers genuinely disagree, and it matters least for the ones everybody computes the same way.
What the dependency list reveals about where the data comes from
`pyproject.toml` names `yfinance` among the runtime dependencies, alongside pandas 3.0 or newer, requests, openpyxl, xlrd, pyyaml, numpy and scipy. By default, though, the toolkit retrieves data from Financial Modeling Prep, which needs an API key, and switches to Yahoo Finance automatically only when that fails; `enforce_source` can pin either source.
Two optional dependency groups extend the picture. The `econometrics` extra pulls in statsmodels 0.14 and linearmodels 6.0. The `mcp` extra depends on the econometrics extra.
The Python floor is `>=3.11, <3.16`, with classifiers for 3.11 through 3.15. The license is MIT and the project is classified as Development Status 5, Production/Stable.
The module notebooks in examples tell you what actually exists
The README's Functionality section is the quickest way to see the scope: Discovering the Sector, Following the Market, Zooming in on Competitors, Weighing Risk and Return, What the Option Market Expects, The Economic Environment, Economic Relations, Comparing the Sector's ETFs, Building a Diversified Portfolio and Following the Portfolio.
Beyond equities, the README says it supports Options, Currencies, Cryptocurrencies, ETFs, Mutual Funds, Indices, Money Markets, Commodities and Key Economic Indicators, and portfolio work gets its own sections even though the README's opening argument is about individual equity ratios.
For learning the library, the README's installation snippet, `from financetoolkit import Toolkit` with a list of tickers and an API key, is the entry point, and the documentation site is the reference for the 500+ methods.
Deploying the MCP server on port 8000
The project is exposed to LLM tooling through the Model Context Protocol, and the packaging supports it properly rather than as an afterthought. A `mcp` extra, a `financetoolkit-mcp` console command, a `server.json`, a `glama.json`, a downloadable MCP bundle attached to releases and links to Smithery and Glama are all present in the repository.
For a self-hosted deployment the Dockerfile is short and shows the intended runtime. It builds from `python:3.12-slim`, installs uv, and syncs only the mcp extra with development dependencies excluded:
FROM python:3.12-slim

WORKDIR /app

RUN pip install uv

COPY pyproject.toml uv.lock README.md ./
RUN uv sync --frozen --extra mcp --no-dev
The compose file then binds the port and passes the secret through the environment, and it declares a named volume for the cache so it survives container replacement:
services:
  finance-toolkit-mcp:
    build: .
    ports:
      - "8000:8000"
    environment:
      MCP_TRANSPORT: streamable-http
      MCP_PORT: "8000"
    volumes:
      - ft_cache:/root/.config/financetoolkit
Note the entry command and the health check that go with it: the container runs `uv run financetoolkit-mcp` and probes `/health` on port 8000 every 30 seconds. The `FT_MCP_SECRET_KEY` variable comes from your own environment rather than a baked-in value, and the compose file notes the server is also already hosted at financetoolkit.jeroenbouma.com/mcp if you would rather not run it yourself.
Why the v2.2.0 cache rewrite matters for repeated calls
The pyproject.toml on the default branch declares version 2.3.0, matching the most recent release, v2.3.0 on 2026-10-25, which followed v2.2.3 on 2026-10-12 and v2.2.2 on 2026-10-10.
The docker-compose file keeps the toolkit's cache directory, `/root/.config/financetoolkit`, on a named volume, `ft_cache`.
Where the arithmetic stops and the data provider begins
The honest comparison is with what you would otherwise use. A commercial terminal gives audited statements, intraday prices, analyst estimates and a support desk, at a cost that puts it outside an individual budget. A hosted API such as a financial data SaaS gives clean JSON and a billed quota. Raw scraping code gives you full control and full responsibility.
Finance Toolkit sits between the last two. It wins on transparency and on cost, and it loses on data quality guarantees, because it inherits whatever Financial Modeling Prep, or Yahoo Finance as the fallback, returns; the README notes the free FMP plan is limited to 250 requests a day, 5 years of data and US-listed companies. The distinction the README insists on, a transparent method versus an opaque one, is real and worth having, but a transparent calculation over incomplete statements is still an incomplete answer.
The last push to the repository was on 2026-11-01, a week after v2.3.0, so the release line is moving. Read the README section for the analysis you care about, check the file behind the formula, and treat every result as reproducible arithmetic on someone else's data rather than as a number of record.
Editorial conclusion
Finance Toolkit earns its place when a metric's definition matters more than its availability, which is exactly the case the README argues with eight different price-to-earnings figures for Microsoft on the same day. The formulas live in files you can read, and the README's functionality sections walk through real analyses. It will not replace a terminal for intraday prices or analyst estimates, and it inherits whatever Financial Modeling Prep, or Yahoo Finance as fallback, returns, so treat the output as reproducible arithmetic rather than as audited data. Start with the README's installation snippet, then read `financetoolkit/ratios/valuation_model.py`, because that file is the argument the whole project rests on.
Frequently asked questions
Where does Finance Toolkit get its financial data?
By default from Financial Modeling Prep, which needs an API key; if that fails, it switches automatically to Yahoo Finance, through the yfinance package listed in the runtime dependencies of pyproject.toml. Everything above that layer, including all 500-plus metrics, is computed locally, which is the point of the project.
What is the difference between Finance Toolkit and Finance Database?
Finance Database is a database of over 300,000 symbols covering Equities, ETFs, Funds, Indices, Currencies, Cryptocurrencies and Money Markets. Finance Toolkit is the calculation layer that turns statements into metrics. The README describes them as complementary: tickers found in the Finance Database can be fed into the Finance Toolkit.
Can I use Finance Toolkit with an AI assistant?
Yes, through its MCP server. The repository includes an mcp extra, a financetoolkit-mcp command, a server.json, a Dockerfile and a docker-compose file that deploys it on port 8000 with streamable-http transport, plus links to Smithery and Glama and a downloadable MCP bundle on each release.
Official sources
Add this badge to your README
If you maintain this project, the badge below links readers to this analysis and shows its maintenance status from the daily GitHub snapshot. Paste the markdown into your README; add ?metric=license or ?metric=stars to the image URL for a different field.
[](https://hysenlabs.com/projects/jerbouma-financetoolkit)Star history chart for your README
[](https://hysenlabs.com/projects/jerbouma-financetoolkit)Was this useful?