Sea Protocol's Grid Orders Flip One Tick at a Time, and the Rest Is a Promise
Sea protocol is the ultimate DEX base on order-book & AMM on Aptos & Sui.Anybody has the right to trade any asset anywhere, anytime!
At a glance
- What is it?
- A Move DEX base for Aptos and Sui whose order book mechanic is a grid that reverses each filled level to the opposite side. The repository itself is five entries and one test command, so most of the design lives in the README's arithmetic.
- Who is it for?
- Sea protocol is worth reading if you are designing an order book on Aptos or Sui, because the grid flip rule, the first-trade min lot size and the scaled price ratio are spelled out with formulas and a worked example, which is more than most design documents offer. It is not something to deploy against on the strength of this repository.
- Can I use it commercially?
- Check first. The repository uses a licence we do not classify automatically, so read its LICENSE file before any commercial use.
- Is it still maintained?
- Activity is slowing. The repository last received commits 8 months ago.
- What is it written in?
- Mainly Move, according to GitHub's language statistics.
Answers come from the project's GitHub data, last synced on November 15, 2026, and from our analysis. They are not legal advice.
Star history
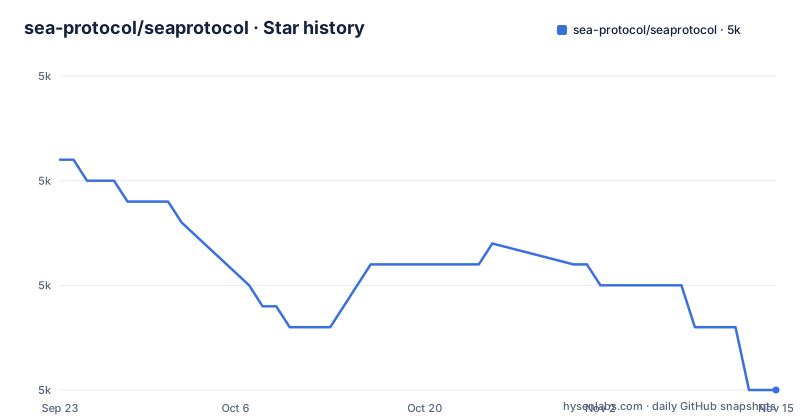
- sea-protocol/seaprotocol5,030 ★ · -11
| Repository | 2026-09-23 | 2026-11-15 |
|---|---|---|
| sea-protocol/seaprotocol | 5k | 5k |
-11 Stars in the last 53 days, measured from the daily GitHub snapshot. Compare with other projects
Editorial analysis
The EVM version was moved out and what remains carries no release tag
The first thing the README says is that the EVM version moved elsewhere, pointing at github.com/sea-dex/gridtrade, and the project homepage is gridtrade.xyz. What is left in this repository is the Aptos and Sui implementation, and it is a small one: the whole tree is .gitignore, LICENSE, README.md, logo/ and src/. There are no GitHub releases at all, so there is no tag to pin, no changelog to diff and no statement of which commit corresponds to which design. The last recorded push is 2026-03-02. One detail worth resolving before you build on it: the license metadata reads NOASSERTION while a LICENSE file sits in the tree, and nothing in the README states which license applies, so read the LICENSE file itself before relying on the terms. Treat the repository as a design document with a code directory attached rather than as a released library.
A filled level flips to the opposite side one tick inside
The core mechanic is the grid order, also known as grid trading: orders placed at regular intervals across a price range, where buy orders are replaced with sell orders when they fill and sell orders are replaced with buy orders. The worked example has Alice placing a grid of eight orders, four on each side:
| Side | Price | Qty | |---|---|---| | Sell3 | 103 | 2.5 | | Sell2 | 102 | 2.5 | | Sell1 | 101 | 2.5 | | Sell0 | 100 | 2.5 | | Buy0 | 98 | 2.5 | | Buy1 | 97 | 2.5 | | Buy2 | 96 | 2.5 | | Buy3 | 95 | 2.5 |
If Sell0 fills, the order receives 100 times 2.5, which is 250 in quote, and that level flips to a buy order:
| Side | Price | Qty | |---|---|---| | Buy | 99 | 2.5 |
When that buy fills, it becomes a sell again:
| Side | Price | Qty | |---|---|---| | Sell | 100 | 2.5 |
Each flip lands one tick inside the previous fill, so the strategy collects the spread repeatedly as price oscillates, and the README frames the result as the order book counterpart of a Uniswap v3 ranged position. The escape hatch is that any order in the grid can be cancelled at any time, so a maker can leave at will and the grid is not locked.
The min lot size is set by the first trade, not by the pair creator
Each pair carries a min lot size, and the README states its purpose plainly: to protect against a Sybil attack. The timing is the part that catches people out. The value is not set when the pair is created. It is set when the first trade is created, and from then on it can be modified at any time the trade price is updated, although doing so is not necessary. Three consequences follow for anyone building on it. The value is set at the first trade on a new pair, and every later trader has to live with it until it is modified. The floor can move after you hold a position, which changes whether your next order is valid without any action from you. And the README does not say who is permitted to change the value, whether resting orders survive a change, or what the default magnitude is, so a client cannot infer any of it and has to ask.
Prices are integer ratios and the u64 balance caps decimals at eight
Because the Aptos standard library keeps coin balances in u64, the coin's decimals cannot be too large and the recommended maximum is 8. Everything else follows from that constraint. Ignoring scale, price is quote volume over base volume. Adding scale, it becomes a ratio of scaled amounts. To keep it integral, the price is multiplied by a large number called the price coefficient, which collapses into a price ratio:
price = quote_volume / base_volume
price = (quote_amount * base_scale) / (base_amount * quote_scale)
price = price_coefficient * (quote_amount * base_scale) / (base_amount * quote_scale)
price_ratio = price_coefficient * base_scale / quote_scale
price = price_ratio * (quote_amount/base_amount)
The practical catch is the last line. It divides quote_amount by base_amount with no mention of what happens to the remainder, so integer truncation is left for the reader to reason about, and a token carrying more than the recommended eight decimals has no documented behavior at all. Both are the kind of detail that decides whether an order fills at the price you expected.
Zero spread stacks post-only orders on both sides of one price
The README calls out a feature it names zero spread: you can place post-only orders with the same price on the reverse side. Its stated purpose is stable coin swaps. In a USDT and USDC pair the order book would hold sell orders at price 1 and buy orders at price 1 at the same time, so anyone can buy USDT at 1 or sell USDT at 1. The design is coherent for assets that are meant to trade at parity, where a spread is a cost the protocol would rather not impose. What the README leaves open is the economics. If both sides rest at the same price, the resting orders never earn the spread that normally compensates a maker, and nothing in the text says who is paid in that state or whether the trade fee still applies. It also does not say what a pair should do when two nominally stable assets drift apart, which is the case the parity assumption is built on.
Trading is mining is a token promise with no contract behind it
One section argues that Uniswap does not allocate tokens to trades, calls that unfair for traders, and observes that traders paid the trade fee and the gas fee but received nothing. The project's answer is that its own token will incentivize traders and liquidity providers, split 50 percent to 50 percent. It is a clean argument on its own terms, but the README names no token, no symbol, no allocation table and no schedule. The trade fee the argument refers to is never defined anywhere in the text either, so the size of the pot being divided is not stated. Read this section as the incentive design the authors want, and note that the 50/50 split is a claim about a token the README never names.
One command runs the Move tests, and nothing tells you how to deploy
The only command in the entire document is a test invocation:
aptos move test -i 1000000000The README does not say what the value passed to the -i flag represents, so a reader cannot tell whether it is an initial balance, a seed or an account amount, and that matters if you want to reproduce the suite. There is no install step, no build command beyond the implicit one, no configuration file reference, no network address and no deployment procedure. src/ is the only code directory, so evaluating the design means reading Move source rather than running a service. The stated rationale for the whole approach is the parallel execution of Aptos and Sui, and no benchmark, latency figure or throughput measurement accompanies that claim. The remaining links are a Twitter account, a Discord invite and a Medium publication, which tells you where the conversation happens but not where the code runs.
Editorial conclusion
Sea protocol is worth reading if you are designing an order book on Aptos or Sui, because the grid flip rule, the first-trade min lot size and the scaled price ratio are spelled out with formulas and a worked example, which is more than most design documents offer. It is not something to deploy against on the strength of this repository. There is no release to pin, no deployment command, no testnet address, and the last recorded push is 2026-03-02, so anything you read here describes an intent rather than a shipped state. Before committing, read the Move source under src/ for the actual rounding and cancellation behavior, check whether the license metadata question is settled, and treat the 50/50 trader and LP token split as a claim until you find a contract for it.
Frequently asked questions
what is sea protocol
A decentralized exchange base written in Move for the Aptos and Sui blockchains, combining an order book with AMM pools. Its distinguishing features as described in its README are grid orders that flip a filled level to the opposite side, a per-pair min lot size intended to deter Sybil attacks, and zero-spread post-only orders for stable coin pairs.
How do I run the Sea protocol test suite?
The README gives a single command, aptos move test -i 1000000000. It does not explain what the -i value stands for, and it documents no install, build, deploy or network configuration steps. All code lives under src/.
What does the min lot size do in Sea protocol?
It is described as Sybil protection at the pair level. The value is not set when the pair is created, it is set when the first trade is created, and it can be modified later whenever the trade price is updated, although that is not required.
How does Sea protocol flip a filled grid order?
When a sell level fills, for example Sell0 at price 100 with quantity 2.5, that level is replaced by a buy order at price 99 with the same quantity. When that buy fills it is replaced by a sell order at price 100 again, so the grid repeatedly collects the spread as the price moves up and down.
Official sources
Add this badge to your README
If you maintain this project, the badge below links readers to this analysis and shows its maintenance status from the daily GitHub snapshot. Paste the markdown into your README; add ?metric=license or ?metric=stars to the image URL for a different field.
[](https://hysenlabs.com/projects/sea-protocol-seaprotocol)Star history chart for your README
[](https://hysenlabs.com/projects/sea-protocol-seaprotocol)Was this useful?