Qlib: Microsoft's AI Quant Platform for Research-to-Production Workflows
Qlib is an AI-oriented Quant investment platform that aims to use AI tech to empower Quant Research, from exploring ideas to implementing productions. Qlib supports diverse ML modeling paradigms, including supervised learning, market dynamics modeling, and RL, and is now equipped with https://github.com/microsoft/RD-Agent to automate R&D process.
At a glance
- What is it?
- Qlib is an open-source Python platform from Microsoft for AI-oriented quantitative investment, covering data handling, model training, and backtesting. It supports supervised learning, market dynamics modeling, and reinforcement learning, with recent integration of an LLM-driven R&D agent.
- Who is it for?
- Adopt Qlib if you are a quant researcher or developer who wants a unified, open-source platform to move from factor mining to model training and backtesting without stitching together disparate tools. It is especially suited for teams already using Python and willing to learn its workflow configuration system.
- Can I use it commercially?
- Yes. MIT is a permissive licence: you can use, modify and sell software built on it, as long as you keep its copyright and licence notices.
- Is it still maintained?
- Yes. The repository last received commits 11 days ago.
- What is it written in?
- Mainly Python, according to GitHub's language statistics.
Answers come from the project's GitHub data, last synced on November 15, 2026, and from our analysis. They are not legal advice.
Star history
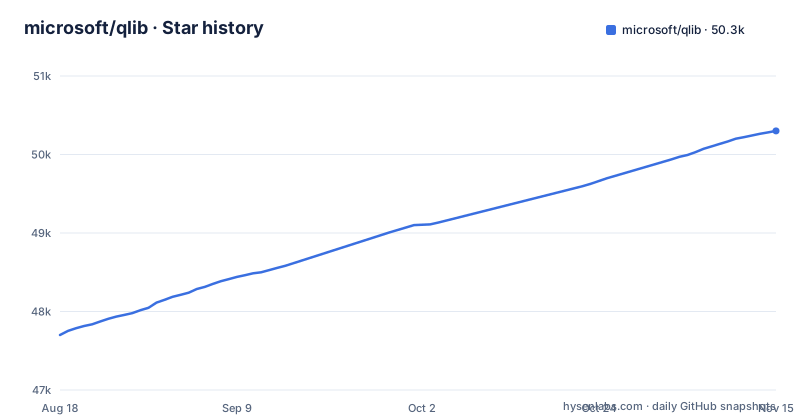
- microsoft/qlib50,301 ★ · +2,600
| Repository | 2026-08-18 | 2026-11-15 |
|---|---|---|
| microsoft/qlib | 47.7k | 50.3k |
2,600 Stars in the last 89 days, measured from the daily GitHub snapshot. Compare with other projects
Editorial analysis
What Qlib Solves and Who It Serves
Qlib addresses a recurring pain in quantitative research: the gap between exploratory modeling and production deployment. Most teams build custom scripts for data cleaning, factor computation, model training, and backtesting, which leads to duplicated effort and inconsistent results. Qlib provides a unified platform that covers the full pipeline, from data ingestion to model evaluation. It is designed for quant researchers and engineers who want to apply machine learning to financial markets without reinventing infrastructure. The README positions it as an AI-oriented platform that supports multiple modeling paradigms, including supervised learning, market dynamics modeling, and reinforcement learning. This breadth means it is not a single-purpose library but a framework for experimentation and deployment. The intended audience is technical: users who are comfortable with Python, configuration files, and the command line. The platform's ambition is clear from its feature list, which includes point-in-time databases and high-frequency data examples, indicating a focus on serious research workflows rather than hobbyist backtesting.
The Core Architecture: From Data to Models
Qlib's architecture, as visible in the repository and documentation, is built around a modular pipeline. The README mentions a point-in-time database, which is a critical component for avoiding look-ahead bias in backtesting. This database stores data as it existed at each historical moment, so models are trained and evaluated on information that was actually available. The platform also includes data providers, such as the Arctic Provider backend, which supports orderbook data. For model training, Qlib offers a range of built-in models, including Transformer, Localformer, TabNet, and DoubleEnsemble, among others. The workflow is typically defined in YAML configuration files, which specify the data, model, and training parameters. This configuration-driven approach allows users to reproduce experiments and swap components without rewriting code. The README also mentions a nested decision framework for high-frequency trading, which suggests a layered approach to decision-making that can handle multiple time horizons. Overall, the design is modular, with clear separation between data, models, and the training loop.
Getting Started: Installation and First Steps
The README points to the PyPI package pyqlib, which is the official distribution name. To install, you would use pip: `pip install pyqlib`. The documentation at qlib.readthedocs.io provides a quickstart guide.. Based on the repository layout, you can also clone the repository and install from source, which is common for projects with native dependencies. The examples directory contains notebooks and scripts, such as the tutorial notebook mentioned in the feature list. The examples directory includes benchmarks, a tutorial, and workflow_by_code.py and workflow_by_code.ipynb, which are the natural places to start running a workflow. The learning curve is non-trivial, as you need to understand Qlib's data format and configuration schema before you can run custom experiments.
The Reinforcement Learning Framework and Market Dynamics Modeling
One of Qlib's distinguishing features is its support for reinforcement learning, which was released in November 2022. This is not a common capability in open-source quant platforms. The RL framework is designed for tasks like portfolio optimization and order execution, where sequential decisions matter. The README lists several pull requests that contributed to this feature, indicating a substantial implementation. Additionally, Qlib includes models for market dynamics modeling, such as HIST and IGMTF, which aim to capture temporal patterns in financial data. These paradigms go beyond standard supervised learning, which typically treats each time step independently. For a quant researcher, this means you can experiment with models that explicitly account for market state changes. The RL framework, in particular, requires careful reward design and environment setup, which is a known challenge in the field. Qlib provides the building blocks, but you must supply the domain expertise.
The RD-Agent Integration: Automating Research
A recent development is the integration with RD-Agent, an LLM-based autonomous agent for data-driven R&D. The README highlights this as a major feature, with a paper published in 2025. RD-Agent supports automated factor mining and model optimization, which could reduce the manual effort in quant research. The integration is not embedded in Qlib itself; it is a separate repository (github.com/microsoft/RD-Agent) that interacts with Qlib. This means you can use Qlib as the execution engine while RD-Agent proposes factors and model configurations. The README mentions demo videos and an arXiv paper, but provides no direct code examples in the README itself. This is a significant shift from a static platform to an automated research loop. However, the maturity of this integration is unclear from the README alone. The paper is from 2025, so it is recent, but you should verify whether it works with your data and models. The idea is promising, but it adds another layer of complexity and dependency. For teams that are not ready for LLM-driven automation, Qlib's traditional workflow remains fully usable.
Limitations and When Qlib Is the Wrong Tool
Qlib is not a complete trading solution. The README does not describe broker connectivity or order routing in the part it covers; its features include online serving and automatic model rolling, but live execution would be yours to build. The platform is research-heavy, with examples for backtesting and model training, but production deployment requires significant additional work. Another limitation is the data requirements. Qlib expects data in a specific format, and while it provides providers for various sources, the point-in-time database requires careful construction to avoid bias. If you do not have clean, point-in-time data, your backtests will be unreliable. The learning curve is steep, as the configuration-driven approach can be opaque to newcomers. For a small team without dedicated quant engineering support, adopting Qlib might be more overhead than benefit. If your primary need is a simple backtesting tool with a graphical interface, Qlib is overkill.
Alternatives and How They Differ
The most direct alternative to Qlib is Zipline, an open-source backtesting library that focuses on event-driven backtesting. Zipline is simpler and has a smaller learning curve, but it does not offer the same range of machine learning models or data management features. Qlib's point-in-time database and configuration-driven workflows are more sophisticated than Zipline's approach, which typically requires you to write more custom code for data handling. Another alternative is QuantConnect, which is a cloud-based platform with a broader set of asset classes and broker integrations. QuantConnect is commercial and offers a web IDE, but it is less flexible for custom research pipelines. Qlib is more appropriate for teams that want to build their own models and data infrastructure, while QuantConnect is better for those who prefer a managed environment. The key difference is that Qlib is a research platform, not a brokerage or execution platform. You must bring your own data and execution layer. This is a trade-off: you gain control and reproducibility, but you lose convenience.
Maintenance and License Considerations
Qlib is licensed under the MIT License, which is permissive and allows commercial use, modification, and distribution. The project is actively maintained, with the latest release v0.9.8 on October 8, 2026, and previous releases v0.9.7 in August 2025 and v0.9.6 in December 2024; the last push was on 2026-10-30. Releases are spaced months apart. The README carries an unreleased-breaking-change notice about artifact loading and links migration guides, and the repository has a CHANGELOG.md, so review those before upgrading. The maintenance cost is moderate: because Qlib is a framework, you will need to keep up with API changes and potential breaking changes between versions. The documentation is hosted on ReadTheDocs, but it may not always be up to date with the latest features, as seen with the RD-Agent integration which is documented separately. For a commercial team, the MIT license is low-risk, but you should still review the license text to understand any patent clauses, though MIT typically has none. Overall, the project appears well-maintained, but you should not assume that all features are equally stable.
Editorial conclusion
Adopt Qlib if you are a quant researcher or developer who wants a unified, open-source platform to move from factor mining to model training and backtesting without stitching together disparate tools. It is especially suited for teams already using Python and willing to learn its workflow configuration system. Do not adopt it if you need a turnkey trading system with built-in broker connectivity, or if your focus is ultra-low-latency high-frequency trading, as Qlib's examples are research-oriented and the platform's learning curve is steep. Before committing, verify that your data sources can be normalized into Qlib's expected format, and check the documentation for the specific models you plan to use, since not all features are equally mature. The latest release is v0.9.8 from October 2026 (after v0.9.7 in August 2025), and the README warns of an unreleased breaking change in artifact loading, but you should still test your own workflow against the latest version.
Frequently asked questions
Is Qlib free?
Yes. The repository is licensed under the MIT licence, and the distributed package pyqlib declares the same licence in its build configuration, with a matching licence classifier. The page mentions no paid tier or commercial edition.
what is microsoft qlib
It is an open source, AI oriented quantitative investment platform aimed at realising the potential of AI in quant investment, from exploring ideas to implementing productions. It supports supervised learning, market dynamics modeling, and reinforcement learning, and the distribution on PyPI is named pyqlib with a version derived from the repository state.
How do I install Qlib?
The distribution name is pyqlib, and installing from PyPI gives you the published release, whose most recent GitHub release listed is v0.9.8 from 2026-10-08. Building from the repository needs a C++ toolchain, because setup.py compiles rolling and expanding Cython extensions, and the build system requires setuptools, setuptools-scm, cython, and numpy 1.24 or newer.
Official sources
Add this badge to your README
If you maintain this project, the badge below links readers to this analysis and shows its maintenance status from the daily GitHub snapshot. Paste the markdown into your README; add ?metric=license or ?metric=stars to the image URL for a different field.
[](https://hysenlabs.com/projects/microsoft-qlib)Star history chart for your README
[](https://hysenlabs.com/projects/microsoft-qlib)Was this useful?